Wednesday, May 25, 2005

Sweet...

Contact Budget for Budget Cheap Travel Insurance in the UK
--------------------------
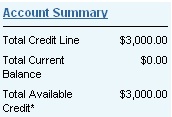


That's a beautiful thing. It's my last credit card account as it looks now.

No, I'm not gloating.

Tuesday, May 24, 2005

New Monitor

The fund drive at my other site was a success. $1500 brought in. That paid off my residual credit card debt, (I had a couple hundred on one of the cards from my vacation last month.) Now my only debt is my car payment. I don't have a cell phone bill, I get unlimited calls from Vonage for $25, I'm paying for my gasoline through the PayPal account, and the only other monthly bills I have are car insurance, electric and cable. (and Rent, of course) The next step is getting my food budget under control.

I got a new 19" flat panel monitor from Dell that I had been looking at...$300...normally it was at $480 or more. I justify this purchase with the fact that my old 15" monitor is now 4 years and I can use it for other things. I plan on doing more and more web stuff and need a good monitor to do it all on. The fact that I got a good deal on it was a bonus. The rest of my money is targeted to boost my checking account and some for savings.

I need to spend some time brainstorming ideas for my other webpages. The goal is still to simplify my life to the point that I can work from home, doing the things I have a passion for.

Save at Overstock.com!

Thursday, May 19, 2005

Why the fuss over PayPal?

Some of you might have wondered why I made such a fuss over PayPal last week. Sure it's nice, but can't I live without it?

Not this week, I couldn't.

See I used it this week to make money. I have another website - several actually - but one that gets quite a lot of traffic. I've had it up and running for three years now. It's not really something I can sell, so I was stumped as to how I could make money from it. I decided in the end, one of the best ways to make money from the page was to do it the old fashioned way.

I asked for it.

The site provides a niche service that many people take advantage of. I'm hesitant to name the site here as I don't really wish for the two to be connected at this time. I want to keep them separate. There's a lot of research involved in keeping up the other site and people are appreciative of it. In the beginning I would get random donations here and there from people, but I decided to make it a concentrated effort. I used to work at a PBS TV station, so I know a little about running a fund raiser. I decided to use similar principles and run two fund raisers a year for my site. A major one in the fall, and a smaller one in the spring. Two years ago, I had my first fall drive, set a goal of $3500 and made it. Last May I set a goal of $1500 and made it. Last November, the goal was $5000, again it was made, and this week I'm again going for $1500. As of this moment, I'm at about $1100 with a day to go.

My point during the drive is to talk about the time and effort I put into the site. (2-3 hours each day) There are also considerable expenses involved in maintaining it. I recently had to double my bandwidth capacity with my hosting company. People are appreciative, and many drop in $10, $25, $50, some even $100. I have them send it via PayPal. Sure, PP skims a little off the top, but for ease of use it can't be topped. I've got the Debit Card from them, and it's easy to move money into my banking account.

There are other ways I make a little money from the site. Google Adsense, Amazon.com Affiliation and some banner ads, but it's nothing compared to the Fund drives I put together. These are the main source of revenue from the web for me. I use the money to pre-pay hosting and design, upgrade equipment and to justify the time I spend working on the site. I've been able to pay some debt down with it as well.

So there you...if you wondered why I was making the fuss over PayPal...there's your answer.

Wednesday, May 18, 2005

Degunking your Personal Finances

I recently received a review copy of Degunking your Personal Finances by Shannon Plate, and after a brief perusal, I am enthusiastically looking forward to reading the whole book. When I do that, I will provide a full review here, but here are a few tidbits to whet your interest. It seems to be laid out similar to the "Dummies" and "Complete Idiot" book series which have proved so popular...however at first glance it appears there is more here than just the basics. This is a pretty big book...334 pages in all.

The book revolves around a 12 Step process that you should follow in order to fully degunk your personal finances. The steps are:

  1. Get your financial life organized and set aside a place in your home to work on your finances.
  2. Create a clear picture of your current financial situation.
  3. Clean up your credit and debit cards.
  4. Get your consumer debt under control by paying it down.
  5. Fine-tune your home mortgage, and put measures in place to lower your household and other living expenses.
  6. Put a program together to boost your savings and investments.
  7. Clean up your credit report and improve your FICO credit score.
  8. Fine-tune and optimize your budget and improve your spending habits for transportation, groceries and other activities.
  9. Get your taxes, employee benefits, and insurance in better shape.
  10. Find hidden money you didn't know you had.
  11. Put your computer to work to help you automate managing and tracking your finances.
  12. Improve your financial security, avoid identity theft, and put a good back-up recordkeeping system in place.
In the book, there are one or two chapters devoted to each of these 12 steps. If you don't have a lot of time, there are also several quick ways in which you can degunk in 15 minute, 30 minute, one hour, three hour and half day segments.

As mentioned, I'm enthusiastic about this book and look forward to reading and bringing you more about it in the weeks to come.

Friday, May 13, 2005

Simplifying your life in 2005

As seen on Lifehacker this morning.

Lifestyle tips: How to simplify your life in 2005

  • Tip 1: Direct debit everything.
  • Tip 2: Cancel call-waiting on your home phone.
  • Tip 3: Make sure you're not always-on.
  • Tip 4: Read more books and long magazine articles, less on the Internet.
  • Tip 5: Cancel your subscription to cable TV, and subscribe to a movie-rental service instead.
Go to the link above for details on each one of these tips.

Or, on the other hand here are Five Habits of Millionaires so you can act like one.

Oh, and by the way, after a phone call from me, my PayPal account is now fully restored. Now I can plan out my fund drive for one of my other sites that will be for next week.

Tuesday, May 10, 2005

No PayPal Resolution

I'm still annoyed with PayPal. I was away for a week, (Thus the lack of posts) and when I got back Saturday night, I had finally received my letter from PayPal with my important 6 digit code that I need to enter on the website so that I can get my account out of "limited access".

I go to PayPal, log in, enter my code, figuring I'll finally have access to my funds, and also send out some invoices. Instead I get the message thanking me for confirming my information, and that now a representative will have to personally review my account and that I should have an answer within 3 business days.

This is borderline rediculous. To clarify, I've had this account for 3 plus years, have always done the verifications and have never had a single issue. I just hope to be back on it in the next couple days...

The vacation was a success, and pretty cheap, too. Other than 15+ hours of driving, the week was relaxing, got plenty of sleep, ate good food and got some sun and beach. Total cost for the week was probably under $500. Sometimes you just need to get away.

Monday, April 25, 2005

PayPal Annoyance

Get a Home Insurance quote from Direct Line in the UK

-----------------------
I'm annoyed with PayPal.

I probably shouldn't be.

I got an email last week informing me that they have "limited access to your account until additional security measures can be completed". Initially, I took this with a grain of salt, as I get these types of emails fairly often, and they're always "phishing" scams. But this email had no link to click on in it, giving me the impression that this might be legit. So I signed into my PayPal account, and sure enough, I'm on limited access. I can receive money and payments, but I cannot transfer money or make any withdrawals until I update my security information.

The reason given is "unusual activity" on my account, which, to me, the only thing I've been doing differently is I've been using my new PayPal debit card to pay for gas in my car and a couple of other purchases. This is unusual, apparently.

So I go through and start completing the security checks. There are three levels you have to complete. I do the first two easily, stuff like changing your password, answering some security questions like mother's maiden name, last 4 digits of SS# and a couple other things. Then the third step. They want your phone number so they can match it to your home address.

There's the problem. I use Vonage as my home phone number and apparently PayPal can't connect a phone # to a physical street address on a Vonage phone as they would be able to on a regular phone. So I fail that test. What they need to do now is mail me, via snail mail, a 6 digit code to my home address, and when I get that, I can go to the PayPal page, enter it, and hopefully complete my security check. They say it should take 5-7 business days to get that code.

Here's my problems. I'm going on vacation next week...leaving this Friday night. If the code doesn't come before then, I won't be able to use my debit card at all while I'm gone. Second, my other website hosting is bill through my PayPal account. If I haven't validated my account before the 1st, the payment will not go through. I will have to make alternative arrangements...perhaps. I'm planning on switching over my hosting the end of the week to a less expensive, but more full-featured plan. That's all part of a busy week here.

I suppose I should be grateful that PayPal is beefing up security in this manner, but I wish my account didn't have to be basically shut down for a week and half and punish me, even though no security was actually broken.

Thanks to all who participated in the guest blog entry with Tripp Friedler, there were some interesting comments posted.

Monday, April 18, 2005

Guestblog Entry from Author Tripp Friedler

This is a post from Tripp Friedler, author of "Free Gulliver" over the course of the next few days Friedler will respond to comments made by readers. We look forward to a good exchange of ideas here on Simply My Life...

First I would like to thank Bruce for allowing me some air time. I feel right at home here because my book is all about simplifying your life. It is about cutting all those pesky little things that tie us down. It is about getting freed.

I have done many things over my career (restaurateur, record producer, fashion photographer) but for the last 15 years I have been involved in financial consulting. I have worked with numerous clients and I began to notice that they all had the same basic issues. They were focusing so much on accumulating wealth that they were forgetting about having fun. My book is about getting rich but it has very little to do with money.

One issue most relevant to many of my clients is retirement. Somehow in our society retirement has become a good thing. In fact, many people today will stay in jobs they hate just to be able to save for retirement. In some ways this is like getting married, coming back from the honeymoon, and stating that you cannot wait for the divorce.

If we look at really successful people, they do not "retire." In fact, Suze Orman who preaches about retirement is herself not retiring. She has plenty of money yet continues to work. She understands that when you do what you love you never want to stop.

I know many people will say, "Easier said than done. I hate my job but at least it pays well." My question is; what is the appropriate trade off between a job you hate that pays well and one you enjoy doing that pays less?

So I would like to end with the following question: Do you think it is smarter to do work you love and save very little or work you do not like and save a lot?

email: TRIPP FRIEDLER
Author of "Free Gulliver: Six Swift Lessons in Life Planning"

Thursday, April 14, 2005

No more credit card debt!

Alright, so the money was transferred to my bank account and I paid the credit card debt. Actually I will still have a balance of about $100 on there, but I will pay that in the next couple weeks and then stick the credit card in my desk where I won't have it with me.

My plan of using my PayPal debit card to pay for my gas is working out good thus far this month, and it's been needed. Things are very tight this month, and in three weeks I'll be spending a week in the Outer Banks in North Carolina. Some friends of mine rent a house out there once a year or so, and it's a huge house and after we all split the cost, it only comes to about $150 per person for the whole week. We also divide up the making of the meals, so that each couple or pair is responsible for providing food on one day. We drive down there, so all in all, it is a very inexpensive week of vacation.

I'll try to get together a snapshot of my financial picture here sometime like I used to do....

More on "Free Gulliver"

More on "Free Gulliver", the book by Tripp Friedler, who will be a guest on this blog next Monday, April 18th.

Scheduled to publish April 16, the book acts as a swift kick in the pants to remind those people who have just finished their taxes that now is a good time to plan their lives.

Free Gulliver takes the conventional wisdom of financial planning -- how to get what you need to do what you want -- and turns it upside down: how to start doing what you want, *now*, and how to deal with the financial fallout.

As a nation gets nervous about Social Security, Friedler reminds us that "you never retire from a job you love." He'll show you how to stop saving for retirement and start building a job you never want to leave: one that will provide you with income into your second century.

Parents struggling to save for college might be surprised at Friedler's advice: Try cutting back on work and sharing that time with your kids, even if it means less money for college. "The time you spend with your children pays bigger dividends than any investment you will ever make."

Tripp Friedler is an attorney, estate planner, chartered life underwriter, and Gulliver-gone-wild. He is the father of three children. Free Gulliver helps people rig their finances to achieve life goals. It's a swift trip. Won't you give it a ride?

A listing for the author's blog tour:

The "Never Retire" Blog Tour
Featuring Tripp Friedler, author of "Free Gulliver"
Starting Monday, April 18, 2005, at the following blogs:

* All Things Financial

* Simplify My Life

* The Budgeting Babe


Here's some more from the publisher of the book:

Do the turbulent waters of a troubled economy find you looking for a life jacket? Are you trying to get ahead but feel like you're treading water? Do you come home exhausted at the end of the day, unable to muster the energy to pursue your dreams in your "spare time"? Do you feel tied down by the little things, unable to tend to your life goals because just tending to your life is too taxing?

Maybe you're a Gulliver? You remember: Big guy, gets in a shipwreck, swims to shore, exhausted, falls asleep. Wakes up in the morning to find Lilliputians have tied him down - - little guys with tiny strings -- so he can't move. Ever feel like Gulliver? Sure you have. We all have. The time has come to cut those knots.

Free Gulliver is a little book for big people. It will help you slice through those knotty problems that keep you from doing what you were put here to do. You remember what that is, don't you? That thing you put on the back burner so long ago an hour in the microwave wouldn't thaw it. That gift you have. That natural talent you can't find an outlet for -- can't afford to pursue -- not until you get your debts paid down, not until the kids are in school, not until the kids are through college, not until you retire... Little things. Lilliputians with little strings. Keeping you from the life you love.

Free Gulliver will show you how to cut through those lines, little by little, and get moving again toward the life you love. It's written by Tripp Friedler, an attorney, estate planner, chartered life underwriter, and Gulliver-gone- wild. Tripp has studied the life plans of the rich and famous and found out -- guess what? -- they're just as stuck as the rest of us. Friedler has made a business of helping people get their lives back on track. He can help you, too.

Free Gulliver: Six Swift Lessons in Life Planning will help you:

Remember what you're supposed to be doing here
Take an honest look at where you're life journey is right now
Free up the time and money you need to be you
Find unexpected ways to express your natural talents
Make a life plan that realistically gets you from here to there

Free Gulliver turns financial planning upside down (as if your finances haven't been through enough upsets lately). Instead of helping you have enough money when you retire to do what you really want to do, it helps you start doing what you want today, because you never retire from a life you love. Free Gulliver will help you find meaning and fulfillment while still generating the income you need to get by. It will liberate you from the little things that tie you down. It's a swift trip. Won't you give it a try?

ENDORSEMENTS

"For those who feel that things have gotten too complicated, too tangled up, too damned crazy, this book offers candid, straightforward, and practical advice. There is real help here, and the calm voice of someone who's been there and found a way to make his own life better. It's the kind of help we can all use from time to time."
-- Alan M. Webber, Founding Editor, Fast Company

"For all people who want to simplify their lives and still reach their goals, Tripp Friedler has written a delightful and useful book. It shows how to clarify your vision and focus on what's important. With real case studies and reference to his own journey, Friedler makes his lessons wonderfully readable."
-- Walter Isaacson, CEO, The Aspen Institute

"Tripp Friedler uses straight talk and apt illustrations to teach how to free ourselves and find the meaning that lies waiting in every life. By following his own passion, he helps us realize ours."
-- Peter White, Wealth Advisor

"This book is terrific. Traditional, financial life planning leaves you believing that the proper asset allocation or security selection will bring happiness. This is not the case. In order to live a full life everyone needs to ask the questions that are presented in this book. Friedler challenges the reader to think, discuss and set the groundwork for a balanced and fulfilling life. It is truly a shame that this aspect has been left out for so long."
-- Peter Ricchiuti, Assistant Dean, A. B. Freeman School of Business, Tulane University and Director Of Research, Burkenroad Reports

"Tripp Friedler, using his own life experiences, takes us on a wonderful journey. Along the way, we learn to better understand how our career and retirement can become more meaningful and satisfying to us. We also get to learn the importance of defining the legacy we will leave for future generations. He helps us enjoy the journey and achieve our goals."
-- Frank Helsom, Former CEO, Bessemer Trust

"With an unusually caring and human voice, Tripp Friedler explains how having a better life comes down to making simple choices. Friedler uses plain language and real-world examples to guide readers through a decision-making process that can profoundly improve their lives. For anyone stressed out about the quality of their life and what the future will bring, this warmly written book will help you see-and realize-your own possibilities."
-- Keith Mcallister, Media Consultant, Former Executive Vice President and Managing Editor, CNN

Friday, April 08, 2005

Paying off Credit Card Debt

I've decided that I'm going to transfer $3000 from my VirtualBank eMM account and go ahead and pay off my credit card debt.

I know some of you are likely saying: "About time!"

Yeah, I guess sometimes I'm a little slow to come to realizations on certain things. It definitely makes more sense for me to do this on several levels.

1) My job is fairly secure, I don't fear losing it and needing to depend on emergency funds anytime soon.

2) If I did happen to have some sort of emergency, I could then use the paid off credit card.

3) Paying off the card means I'm not paying interest on that debt any longer, and also means I have one less monthly bill to pay. (Simplifying my life...)

4) I can then take that monthly payment I would be using to pay the credit card, $100 or more, and split it between the VirtualBank, ING Direct and my car payment.

5) With the savings of that interest, my savings accounts will be worth more, because the interest I'm gaining on those accounts won't be offset by the interest I'm losing on debt.

6) This will leave me essentially just one source of debt to my name...my car payment. My life will be simpler, as noted above. My monthly payments will now be:

Rent
Car Payment
Cable/Internet Service
Vonage Phone Service
Car Insurance
Electric Bill
2 Savings Accounts
Food
Gas (hoping to pay that using PayPal debit card each month)
Recreation

Wednesday, April 06, 2005

Orange Savings Account Opened

I took another step in making sure I'm saving money and having it spread around a little bit. Still haven't taken the step of investing yet, but now having $50 a week automatically deducted from my checking account each week, ($25 to two different accounts) should help me put something away.

When I bought the Quicken software last week, I installed it that night and noticed the icon that it put on my desktop plugging an offer to get $50 for opening an ING Direct Orange Savings account. I had thought about creating a second savings account to use for larger ticket items or vacations while still maintaining and not touching my "Emergency Funds" sitting over at VirtualBank. After reading earlier this week that ING Direct had raised the APY in their Orange Savings account to 3.00% I went ahead and decided to open the account.

It took less than 5 minutes to fill out the online forms and link my checking account. I initially funded the new savings account with only $50. Now looking at it this morning, my $50 is in there, as well as my $50 bonus for opening the account. In addition I set it up so that each Thursday $25 will be transfer from my checking account. So now I am sending $25 to this new account and $25 to the VirtualBank account.

In other financial news...I canceled my personal cell phone this week. My contract had run out in January, and I have been provided with a cell phone from my work, which my boss has told me is perfectly fine to use for personal calls, as there are a ton of minutes in the plan. So that will save me approx $80 a month, which is now going towards the Orange Savings account.

I've also been able to make a little money each month on one of my other web ventures, and that money comes to me via PayPal. Last month I got a PayPal debit card which allows me to use the money in my PayPal account anywhere I can pay with a credit card. I've decided that I'm going to use that account as much as I can to pay for the gas in my car. Right now my short term goal is to make enough coming into PayPal each month to pay for my gas. That's going to require me to be making about $300 a month. If I can do that, I will then put that extra $300 towards my credit card debt each month.

So there's a few things I'm doing financially right now...

Monday, April 04, 2005

Book Excerpt: "FREE GULLIVER: Six Swift Lessons in Life Planning"

Another excerpt from FREE GULLIVER: Six Swift Lessons in Life Planning. On April 18th, the author of the book, Tripp Friedler will be a guest on this web site. He will post an introductory comment, and then check in periodically during the next few days to respond to comments posted in response to his. It should be a great opportunity to share some knowledge and get some good information and advice.

Staying in a job you hate is crazy.

The first question I ask clients who want to talk about retirement is simple: Why? I try to get them to rethink the concept of retirement by defining the word. Most definitions I get are a variation of a simple idea: "Doing what you want, when you want." Under this definition, most people who love their jobs are already retired.

Look at Michael Jordan. Here is a man who so loved what he did that he refused to retire -- in fact, he added two more championships to his name. Many celebrities, athletes, actors and television journalists continue to work well beyond the "pinnacle" of their careers. While they might not have had the success of their youth, they were still productive. Their love of their profession was so strong that they refused to quit. Why should you quit?

Next I ask my clients what part of their work they most enjoy. What would they like to continue doing into retirement? Most of us have in our jobs a few tasks we love, and the luckiest of us have a whole day filled with enjoyable activities. I ask my clients to identify these pleasurable activities, and then try to make those tasks compose a majority of their time at work. I once heard a great line that sums up this philosophy:

Frank Sinatra did not move pianos.

The point is clear: focus on your passions and talents, and try not to get bogged down in the chores you hate. Be a Gulliver -- live large -- and don't let the little things tie you down. If you concentrate on what you love in your work and pursue it fully, your "Golden Years" can begin today.

RETIREMENT PLANNING EXERCISES


1. List the things you love most about what you do for work.


2. Do you love these things enough to continue doing them during your retirement?


3. What percentage of your work time do you spend on these activities?


4. What can you do right now to increase the percentage of time spent working on these activities?


5. What do you think you could get paid to do only those activities you enjoy so much you'd continue to do them after you retire?


6. Do you think you can live on that income, considering the other resources you have (current savings, social security payments, etc.)?


7. What steps can you take to increase the income you earn from doing these activities?


8. List people you think have retired successfully.


9. Explain what you admire about their retirements.


10. How can you emulate what you like about these retirements?

Tuesday, March 29, 2005

Giving Quicken a whirl...and a Book Tour!

Last month I chronicled some of the tools I use to keep track of my personal finances. I related that each of the ones I use has some shortcomings. In the comments to that post, Quicken was mentioned as a possible solution. I had also been looking for some sort of simple business software to keep track of income and expenses from another website that I maintain. Get some low-level experience at running a business, if you will. So I bought Quicken 2005 Premier Home & Business . I have never seen a product so severely ravaged by reviewers on Amazon.com. I decided to get it with an open mind and see if it could help me out.

I only had time to quickly set up the software and enter a few things. My first impressions was that this was going to take some time to get used to. Predictably, the things that would not sync up nicely with Money (my Credit Union, my TIAA-Cref retirement account) worked great with Quicken. My credit cards (CapitalOne) and my Money Market account (VirtualBank) did not have online features. I need to figure out the business side of things, though I was able to create an invoice, and even add my logo to it. I will continue to try it out. (While keeping my Money program updated and see where I decide to stay.

Book Tour

On another note, there is a new book on the market entitled Free Gulliver: Six Swift Lessons In Life Planning. Next month on April 18th, the author of the book, Tripp Friedler will be a guest on this web site. He will post an introductory comment, and then check in periodically during the next few days to respond to comments posted in response to his. It should be a great opportunity to share some knowledge and get some good information and advice.

Here's part of the introduction to the book, and I will have some more from it as we get closer to Mr Friedler's appearance.


Never Retire

by Tripp Friedler

According to older dictionaries, the definition of retire is "to put out of service, to withdraw." Anyone who has been lucky enough to retire his debt knows this and hopes it never returns. But when your old car gets retired, it doesn't move to the beach. It ends up in the salvage yard. Given the definition, most people would not like to be retired.

How is it that retirement came to be seen as such a good thing? Everyone you talk to wants to retire by the time they reach 60. This book takes a different view of retirement by starting with a very simple premise:

No one wants to retire from work they love.

Beverly Sills, who enjoyed a long and respected career as a star soprano, retired from singing to become chair of the Lincoln Center. In her early seventies she retired from that position, only to reappear six months later as chair of the Metropolitan Opera. "So I smelled the roses and developed an allergy," she told The New York Times.

Ms Sills, like most of us, did not want to be put out of service. Many people in their eighties lead productive, active lives, whether they're working or not. My grandfather died at 95 and worked until he was 92. He didn't do it for the money; he did it for the love of work.

The average age of retirement has plummeted from 70 in 1930 to 62 today. In the same time, the average American's lifespan has increased from 48 to 72. If we start working at 22, expect to retire at 60 and live to age 82, then our retirement comprises almost 27 percent of our entire lives. The implications of these statistics are serious, both personally and financially -- as well as for the national budget deficit.

We no longer worry about living long enough to enjoy our retirement. Now we worry about living so long that we run out of money. We have put a lot of pressure on ourselves to have a large nest egg ready for retirement. Out of fear, too many of stay in jobs we hate in order to save a little more. It bears repeating:

Staying in a job you hate is crazy.

Stay tuned for more to come...

Thursday, March 24, 2005

Still thinking...

Still haven't decided the best way to handle my investments. What I am doing starting immediately is to start taking $25 each week and putting it into my savings account. This way, once I decide, I'll already have a little bit set aside to start with.

It's slow, but I'm getting going. $25/week automatically going into VirtualBank, (Emergency Fund) and now $25/week going into savings, but earmarked for an investment account. I routinely pay $100 more a month on my Jeep Payment, and around $50 extra on my Credit Card.

The rest is towards bills.

I'm looking forward to the release of the upcoming book "Degunking Your Personal Finances" which will be published next month by Paraglyph Press. I hope to be able to bring you some excerpts from it fairly soon.

Monday, March 21, 2005

Investment Dummies

Another column for which I obtained the right to re-publish here.

Are You An Investment Dummy Like Me?

by: Jack Humphrey

I am good at a few things. I can certainly market well and I consult with others about how to bring more attention to their products and services on the internet for a living.

I am a fair musician. I love music and play all sorts of percussion instruments and even dabble with the guitar.

I can cook better than most guys. I can survive in the wild with nothing more than a good sharp knife.

But ask me how to best manage my investments and grow and protect my wealth, and I am like a deer staring into the headlights of oncoming traffic. Paralyzed with doubt, fear, and inexperience.

Much like my clients are when they come to me for marketing advice.

It wasn't until a new client came to me with an idea for a new book he had written on active investment strategies called "Scientific Wealth Strategies" that I realized I might not be far from figuring this whole investment and wealth protection thing out for myself.

In fact, just by consulting with him on the marketing of his book I picked up a lot of new information that has taken a grand portion of my doubts and fears away.

As I began to wrap up our contract I found I was looking more and more at the information in his book from a personal interest as a solution to my worries about whether I was doing everything right with my investments.

First thing I learned is that I was following the vast majority of others who think the same way about investing. "Throw it in something we think is safe and leave it there." And I realized that we are all being lulled into low return funds and investments masked as great returns in a bad economy.

Then I learned what I could do to take the same amount of capital I had in low return investments and actively manage it for far greater returns than what most people generally assume are the best returns you can get these days with 401ks, IRAs, and stocks.

In short, I was learning about investing on my terms. I was learning because my client, C.C. Collins, had chosen to write for people like ME instead of a bunch of learned investment "geeks."

Finally someone had written about investing strategies in a language that I could understand and about strategies I could feel comfortable in applying without feeling as though I was being a risk taker or putting my money in jeopardy.

This is no small feat. I feel most people who are like me are conservative with their investing, and don't become active in the management of their investments, because we much prefer the relative piece of mind we get from letting a "professional" handle the decisions.

Now that I feel more comfortable in the knowledge I have gained from this easy to understand yet incredibly powerful source of investment and wealth buidling knowledge, I have no doubt my investment future is much brighter and is going to bear much more fruit than the track I was on before I met C.C.!

So if you are an investment "dummy" like me, I strongly urge you to take the first step in becoming a relative investment "whiz" by checking out Scientific Wealth Strategies for yourself.

It will really empower you to take charge of your investments and push you to get more from your hard earned dollars than you are currently netting!

Scientific Wealth Strategies
eBook and Software with calculators, investment terminology definitions, and many, many more useful tools. http://wealthscientist.com

Copyright 2004 Jack Humphrey

About The Author

Jack Humphrey is the author of a popular website promotion course called Power Linking at http://power-linking-profits.com and CEO of WebFoxMedia.com http://webfoxmedia.com where he consults for companies in online marketing strategies and traffic generation.

Saturday, March 19, 2005

Decisions, Decisions

I appreciate the various bits of advice and encouragement in the comments to my last post. (No Neville, I'm not sending my money to you) I looked around here and there, especially at Vanguard. That site was recommended to me in a couple of comments as well as by a friend of mine last summer. I thought I had checked it out at the time, but decided to double-check. Now I remember why I didn't do it at the time. It seems to me, maybe I'm wrong, but the minimum you can starting investing there in Mutual and Index funds is $3000.00. I don't have that in my checking account to use, and I don't want to take my emergency money and invest it all in that fashion.

I still may use Sharebuilder, if I did that, I would need to find specific stocks I want to invest in...which takes a lot of time to research everything...and I would set up a $25/week transfer to the Sharebuilder MoneyMarket account, and then, perhaps once a month I would take that $100 and invest it. That's about the best I can come up with. I think I really want to do Mutual Funds or even Exchange Traded Funds. I'm still such a dummy at this, that I can't really even tell if I can invest in those through Sharebuilder.

So I guess I'm still trying to figure out where to start.

Wednesday, March 16, 2005

Investing

Back in December, I took my first babysteps in the field of investing. A mere $200 in a Sharebuilder account. I think I want to do more. I can't do a whole lot, but I need to be making some of my money work harder for me. I have about $4500 sitting in my VirtualBank EMoneyMarket account, currently earning 2.57% APR. It's not bad, but it's not at the inflation rate either. The reason the money is there, is that it is my emergency fund. I need to to get a reliable return and still be easily accessible.

I'd like to do more with the Sharebuilder. Right now I send $25 a week toward to the eMM account, I'd like to send the same amount to Sharebuilder. It seems the safe thing is an Index Fund. The S&P 500, something along those lines. Would that nominal amount even do anything for me? Would I be better off taking that small amount and going for some stocks?

There are a lot of "beginners" websites out there for investing. They're still all over my head. You're supposed to "research" thoroughly any stock you invest in. How do you do this? Inquiring minds want to know simple answers. I haven't gone out and bought "Investing for complete Idiots" but I'm tempted.

What's the best resource for someone starting completely from scratch? No background. Just the facts, ma'am. Where do I turn to find a simple, easy guide for what I want to do, namely take $25 a week and put it somewhere where it generates more than the current inflation rate, so that I'm actually getting ahead a little bit?

Throw me a fricken' bone people. I'm the blogger...need the info...

Tuesday, March 15, 2005

Organization

I came across this article recently and obtained permission to re-print it here. There's nothing really profound contained within it, however I think that it contains some good overall strategy for keeping your financial life organized. (The author is from Australia, thus the usage of "organise" throughout.) It's simply a series of good reminders and and overall strategy for keeping things under control.

Make the Most of Your Money

by: Lorraine Pirihi

I'm always amazed that so many people spend most of their life at work and totally neglect their personal affairs.

Many of the business people I work with want their professional lives to be in order, and admit that their personal affairs are in chaos.

They have no systems for handling this most important area. The household paperwork is disorganised…piled up in a corner of the house…somewhere. They have no idea where they spend their money and often have no plan for their financial future.

If you do not organise your personal life, you won't have much of a future to look forward to.

Avoid the excuses that you are too tired, don't have the time, and don't know how.

Here are several tips to get you started:

Set up a filing system to store your paperwork.

File your papers in categories: Bank, Car, Children, Home, Medical, Insurance, Investment, Tax, Utilities etc.

Organise direct debits for regular bills.

Read, sort and action your snail and e-mail daily. This will avoid a big build-up.

Make a note in your diary when you need to remember to do things.

Check your bank accounts weekly via phone or the Internet to keep tabs on your money.


Allocate a particular day and time each week to review your personal affairs.

Get educated - attend seminars, read books and listen to information on wealth creation. (Our fortnightly Event Update often advertises worthwhile events that will help you). Having knowledge will make it easier to make decisions and take action.

Organising Your Financial Future

This area should be top priority. If you do nothing because it's too much effort well think about this.

What would happen if you lose your job, have an accident and receive no income for 6 months? How would you (and your family) survive financially? Do you have your insurances in order?

Where will you be in the next five years? Maybe retired and on a pension? Or perhaps you have superannuation you hope will be enough to live on? Unfortunately too many people are under false illusions about how superannuation will be the answer for a secure retirement.

Hope is not enough. You have to be pro-active and seek out people who can help you. But be careful who you take advice from and what is the motivation behind them "selling" you their ideas.

Educating yourself on how to make the most of your hard-earned money so you can create wealth should be a high priority. After all, if you're not interested in securing your financial future, who is?

The Final Word

If you take control of your personal affairs you will have peace of mind and know that you are making things happen.

I once heard someone say: Some people make things happen, others watch things happen and others wonder what happened. What do you choose to do?

About The Author

Lorraine Pirihi, principal of The Office Organiser is Australia's Personal Productivity Coach. She specialises in working with businesspeople showing them how to dramatically boost their productivity, reduce the stress and the mess in their lives and have more time for enjoying their life.


lorraine@office-organiser.com.au

Wednesday, March 02, 2005

Show me the money!

Multiple streams of income.

That's a phrase that has resonated in my head for a number of years. It's absolutely a solid idea. You have a number of sources of income coming in, and that means that if you happen to unexpectedly lose one, you have other places to turn for income.

Sounds simple in theory. Putting it to practical application in your life may well be another. Time constraints are a factor, the amount of work you have to do to generate that additional revenue may be another. The ideal is something that you set up, have very little maintenance to perform, and just sit back and collect the money. Realistic? I haven't found one yet.

I currently have two sources of income. My day job, and another website that I operate. On that site, which I prefer to keep separate from this, I don't sell anything. Revenue is generating from Google Adsense, occasional advertising from people who approach me, Amazon.com affiliate sales, and a couple PBS-style "fundraisers" that I do during the year to raise funds and reward the work I put into the site. However, this isn't close to a full-time venture, though I'd like it to be. I spend a couple hours on that site each morning, and in total bring in anywhere between $100 and $300 a month on a regular basis, but my last fundraiser brought me a significantly larger sum in one month. I didn't start out with the intention of making money from that site, it's more of a passion, a little money is a nice side benefit.

I'd like to do more. Obviously, if I lose my day job, I'm not going to be able to support myself and pay my bills based on the website. The amounts are unbalanced. I need a couple more sources of income. More websites come to mind, but you've seen my track record in updating this one, so time is a factor.

What are some ways of creating multiple income streams:

Get a second job

Create a side business that generates regular income

If you have some money, you can have income from interest, dividends and investments...

I'm stumped after that. The second one would be the most realistic for someone in my position, but I wouldn't be able to spend a whole lot time on it. Then I have to come up with the idea. If it's something I enjoy doing already, then all the better, because I'm going to keep up with it.

I'll need to think about this more.