Wednesday, August 31, 2005

Month End Update

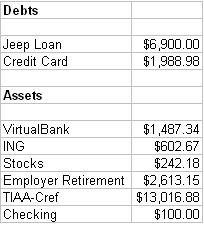
Here's something I haven't provided the last couple months, a financial snapshot.


I'm a little disappointed in my progress at this point. The credit card balance is back up there, and so I'm sort of starting from scratch. It went to a good cause, but it's still an blight on the record here.

The car payment has come down a bit since the beginning of the year, and the other positive balances have gone up.

In the coming months, I expect to be investing in a bit of jewelry. That's sort of what the VirtualBank funds are earmarked for at this point.

I may need another big November to put me back into where I'd like to be by the end of the year. I was hoping to actually forego the fund raiser on my other site, but it's looking like I'm going to need to go to that well once more.

I'd like to have the car and credit card debt paid off by the end of the year. Four months to make it happen and go into 2006 with a pretty clean slate!

Monday, August 22, 2005

Overdue Update

For some reason, I haven't had much to report in this space as of late. That's unfortunate, because I know people are stopping by everyday and I've had nothing for them.

What's been happening in my financial life? Not a whole lot, I did that recent balance transfer, and then last week I made a financial gaffe and realized I hadn't sent out my Jeep payment until the day before it was actually due.

This week I will be spending money, but hopefully not using any credit. Darcy and I are going with another couple out to San Francisco, where Darcy is originally from. We got $99 fares each way from Independence Air from Manchester NH to S.F. so that was quite reasonable. On Friday night we're going to a Giants game and on Saturday we'll be doing some wine tasting in the Napa Valley.

I'm going to be "photoblogging" the trip on one of my other blogs, that blog has a food theme, so the pictures and things I'll be blogging about will involve food and wine for the most part. You should start seeing photoblog entries on that site starting Thursday evening. The site address is at http://parttimegourmet.blogspot.com/ So be sure to check that out if you're interested.

I'm hoping to keep costs relatively low for the trip, but we'll see how that all goes.

I've tried to keep things relatively on-topic for this blog, so much so that I guess recently that I've had bloggers-block for this address. You would think that wouldn't be the case, since we all use money every day.

Friday, August 12, 2005

Balance Transfer Done

I have successfully engineered my first ever 0% APR balance transfer.

When I received my card from HouseHold Bank, I called to activate the card, and while on the phone with them, the very helpful representative assisted me in making the balance transfer....right over the phone.

This was on Wednesday, and this morning I went and checked my Capital One balance, and it is all paid off once again. So now I have 12 months of 0% APR to pay off that balance, though I plan on paying it off much sooner than that.

I have to say, I was very impressed with the rep from HouseHold Bank. She was extremely friendly and helpful. It was nice to be treated as a real person, rather than the second rate credit risk talkdown that I have been subjected to in the past from other credit companies. Here's hoping it continues.

Tuesday, August 09, 2005

Trying the balance transfer trick...

Over the course of the last couple weeks, I've suddenly rung up almost $1800.00 in credit card charges. This is disappointing to me, after having worked hard to pay them off, but none of the purchases were frivolous, and as mentioned in the previous post, most of them were to help my parents out.

I was dreading paying the interest charges again, as there would be no way I'd be able to pay the whole balance off this month.

Then it occurred to me, I have a brand new credit card on its way to me which is offering 0% financing for a full year and free balance transfers. So I'm going to try something that I've only been able to read about others doing; I'm going to transfer that $1800 to the new card and save the interest until I can pay off that balance in the next few months.

I'll keep you posted as to the progress of this transaction, as mentioned, I haven't received the card yet, but I do know it is on the way and I know the credit limit I've been given.

Monday, August 01, 2005

Unexpected (but worth it) Expenses

This weekend saw my credit card balance go up to $1000 after being paid off a couple months ago.

This weekend there was a family reunion up at my parents farm. About 100 people were in attendance, some of whom I hadn't seen for several years. After everyone left, Darcy and I stuck around to give my parents a gift for their anniversary.

About 8:00 my dad went out to milk the cows, and then came running back in with chilling words: "We've got a fire here!" I looked out the window and could see flames coming out of the barn. I ran to the phone to call 911, but it was dead. My sister grabbed her call phone and dialed for help as I ran down to the barn, my father was there inside spraying down one of the walls with a hose, it hadn't spread too far yet, so he was able to get the flames under control while the fire department was on it's way.

In the meantime I was getting the cows in the area out of the barn. One cow directly in front of the fire was was burned slightly on the ears and hurt herself as she pulled back from the stall and yanked on her chain, her neck rubbed a bit raw. We got her out ok though, along with the other ones.

Once the fire department got there, they tore out some of the walls to make sure there wasn't still fire or embers in there that might ignite again. They figure it was an electrical fire, perhaps from a radio. They were there for a couple hours. Once they left, there were a whole number of problems that were left to figure out.

There was no electricity in the barn - no lights, no power for the vacuum milking system.

The Cows need to be milked - if you don't milk cows on schedule, they might actually start leaking milk, and if they're not milked on time, the milk can actually start to sour inside of them, causing an infection.

Thankfully there was still power to the milkroom, where the milk is kept in a chilled, stainless steel tank.

A neighbor (who is also a farmer) came up and helped get some things sorted out. They figured out that they could get the vacuum pump working for the milking, but still had no lights. It was just about closing time for the local Wal*Mart, so Darcy and I ran down there and bought a small generator, a couple sets of floodlights, some long extension cords, a a fan and a couple other items. Ran close to a $1000 - put it on the credit card, but didn't think twice about it.

Get everything set up about midnight and was able to milk the cows and close up around 2:00 am. A long day.

I'm going back over there today, and if there are more needs, I won't hesitate to put more on the card to help them out.

Wednesday, July 27, 2005

What is CSA?

I've gotten a couple questions asking if I have more information on the CSA that I mentioned a few posts ago. This morning's Boston Globe had a piece on Community Supported Agriculture, where the farmer sells shares of "stock" in his land each spring, and all the "shareholders" receive a portion of the produce grown on the land, according to how big their "share" is.

A pretty neat idea.

Farms' investors enjoy the fruits (and veggies) of their labors

This is one of the ideas I'm kicking around for putting the land on my parents farm to better use in the future...part of the "simple life".

I'd like to be able to leave the rat race and support myself on a variety of income sources, this could be one of them. It's a long ways off, but you'll probably see more of this type of stuff and thinking in this space moving forward...

Thursday, July 21, 2005

Coming soon...

I will post something soon...I promise.

Maybe a look at some pretty major expenses I could be looking at in the next 12 months, and how I should handle them.

Some major things that could be on the docket...
  • Engagement Ring
  • Wedding
  • Honeymoon

Further out:

House down payment

Things could be getting interesting, but I need to come up with a plan first!

Thursday, July 14, 2005

Should you quit your job?

Mark Morford in the San Francisco Chronicle has a fascinating article today looking at those who are leaving their "safe" jobs to pursue other things.

Call it "the cafe question." Any given weekday you can stroll by any given coffee shop in the city and see dozens of people milling about, casually sipping and eating and reading and it's freakin' noon on a Tuesday and you're like, wait, don't these people work? Don't they have jobs? They can't all be students and trust-fund babies and cocktail waitresses and drummers in struggling rock bands who live at home with their moms.

Of course, they're not. Not all of them, anyway. Some are creative types. Some are corporate rejects. Some are recovering cube slaves now dedicated full time to working on their paintings. Some are world travelers who left their well-paying gigs months ago to cruise around Vietnam on a motorcycle before returning to start an import-export business in rare hookahs. And we look at them and go, What is wrong with these people?

It's a bitter duality: We scowl at those who decide to chuck it all and who choose to explore something radical and new and independent, something more attuned with their passions, even as we secretly envy them and even as our inner voices scream and applaud and throw confetti.

I'll admit, part of the reason for this site is to Simplify My Life so that I can do just that. It's not something you can enter into on a whim, however, I realized that I needed to get my financial house in order to be able to even consider living a simpler life on reduced income.

I have my ideas. My parents have a farm, and I've kicked around the idea of building a house there (They've said they're setting aside house lots for my sisters and myself) and working from home there...the idea being twofold, my living expenses might be less, and I can be available to help out my parents when they need it.

I could look into growing certain crops, organic even, or doing something called a CSA (Community Shared Agriculture) the opportunities are there, the land is there, and my parents struggle at times to get by.

I've spilled a lot here, and more will come as we go on, but the dream to Simplify My Life lives on...

Wednesday, July 13, 2005

Checking the mail

Went to the mailbox and found a couple of items of interest. Well, to me, any way.

The first was a notice from Capital One that they have actually increased the credit limit on one of my cards. Granted, it's only $500, but it's the first increase that I have received since I got the card, probably about four years ago. I don't plan on going out and taking advantage of my higher credit limit, but still it's nice to have them giving to me with having to ask them.

The second was a credit card offer. Yes, I do get plenty of these each week, and most of them are from Capital One. This one however was from Household Bank and is the first time that I am actually considering applying for the card. The offers I get...most of which are from Capital One...mostly consist of six months of 3.7% APR, followed by a 12.99% rate later on. This card would have a full year of ZERO % and an 11.24% rate after that.

Now I realize that that rate is probably still much higher than anything a lot of your would accept. For me, this is actually the best offer I have received in the last few years. I'm considering opening the account, just to have it. I currently have two credit cards, both zero balances, and both with Capital One. Does it make any sense to open an account with another company, but not use the account except in case of emergency?

Now, these are minor items, yes. But to me, in looking at them and thinking about it, it appears to be that I can take the increased credit limit and improved offers to mean that my credit is slowly rebounding. Without going and pulling my credit score to see for sure, I can use indicators like this to assume that my own personal "stock" and credit worthiness is slowly on the rise...

Thursday, July 07, 2005

Another Small Step in Investing

So I looked at my direct deposit paycheck stub today, and realized that my meager cost of living increase has gone through. Before taxes, I will now make about $68 dollars more per month.

Very exciting, I know.

So I decided to take that money and do something with it. It's not much, but maybe I can turn it into more. Give myself a bigger raise, as it were. I already have a Sharebuilder account and decided to go through their "Portfolio Wizard" tool and see what it would recommend. I followed the steps and it recommended a couple of investments to make. Coincidentally these were both investments I had looked at already and was interested in making. So I set up $50 a month to go towards those investments.

It's not much, I realize. But now I have $250 per month that is being taken directly out of my check and placed into some sort of Money Market (Virtual Bank or ING) and Investments (Sharebuilder)

We'll see what happens.

The 11 Best Money Saving Ideas of All Time - Part 4

The 11 Best Money Saving Ideas of All Time - Part 4

by: Palyn Peterson

At any time in history, no matter what the current state of the economy, no matter what the current trends, no matter what the unemployment rate is or where interest rates lurk, some money-saving ideas stay true.

Some of you may have heard of these ideas before, others may be entirely new to you. But whether you are familiar with these super secrets or not, it will be well worth your while to put them into effect in your own life. The magic they will work on your financial life is guaranteed. I urge you to put them to work - any one of these could change your life! Big changes come from small steps. One plus one does equal two, so if you add one from eleven different places, you will see big results.

This is a four part series giving you advice on saving your hard-earned money in a variety of down-to-earth ways. Nothing here is anything that anyone can't do on a daily basis.

Amazing Money Tip #9

You must set short-term goals and long-term goals. If you don't know where you are going, how do you expect to get there? It's simple but powerful logic. When you have a target sitting out there somewhere in the future, a target which is your goal, it can almost act like a magnet that pulls you toward it.

Setting solid goals which are attainable, yet still a challenge, have proved time and time again to be one of the most powerful methods of achieving wealth and success ever developed. It has been demonstrated in corporate training schemes. It has been used successfully again and again by countless individuals. Setting both short term goals and long-term goals has the effect of focusing your mind like a laser beam. It pulls you along toward higher and better things. It gives solidity to what you are trying to accomplish, and thus makes that which you want more real and likely to come into your life.

As you have probably heard, it is best to write your short- term and long-term goals down on paper and then post them somewhere in your workplace and home. The first thing you should do every morning is look over your goal list, and then put together your Top 10 to do list which will move you toward your goal. The last thing you should do every evening is review your short-term and long-term goals, and tell yourself as you go to sleep that you are going to do everything in your power to make those goals a reality in your life.

Amazing Money Tip #10

Invest your money and make it work at multiplying itself. Saving money in a savings account is important as we said above, but the 2.3 percent interest rates most banks give you is not even enough to keep pace with inflation.

You must do more than save your money -- you must invest it. That means financial vehicles with super-high rates of return, such as mutual funds and stocks, or the more risky commodity markets.

A $5,000 investment in commodities can return you 10 times that amount -- $50,000 --in just a few weeks, although you could easily lose it as well. Invest your savings into a long term certificate (CD). You can often get one with an interest rate up 4.5-5%. They are 100% safe, and still give you a much better return than normal savings accounts.

The bottom line is, you should take a portion of your savings and put it in a high interest or high risk investment plans. That's the way to really get ahead.

Amazing Money Tip #11

Have fun! Yes, this tip easily makes my list because it is so essential to your success. The great writer Ray Bradbury once said in an interview: "If you are not having fun, you might as well forget it. Do everything you do with joy and you'll be successful." You need to be having fun to stay positive, and you need to stay positive to make money. So come on! Get out their: laugh, clap your hands, live! Have a blast and rake in the cash! The world is waiting for you!

I hope you have learned many new ways to save your hard- earned money, and enjoy your day-to-day life more. Remember, nothing discussed in this 4 part series is anything that you can't do. If you put this information to good use, it is guaranteed that you will benefit from it.

Copyright © by Palyn Peterson

mailto:palyn@futureinternetmarketing.com

About The Author

Palyn Peterson publishes the acclaimed Advanced Internet Marketing News. A professional newsletter with a refreshing perspective and a strong focus on no-cost techniques. http://FutureInternetMarketing.com. FREE Tips, Tricks, Tools, Resources, eBooks, and More!

This article is free to publish with resource box. If using this article, please send a brief message to mailto:palyn@futureinternetmarketing.com

Tuesday, July 05, 2005

Sneaky Capital One?

Every month like clockwork, Capital One sends me two small books of checks, one for each of my accounts. They're so you can write a check and it will be charged to your credit card account. I actually used a couple of these over the winter because the big selling point on them was that your interest rate for purchases made with the checks would only be 1.9% (I think) Something very low like that as opposed to my regular rate, which is in the mid teens.


So today, I got my two checkbooks and I actually looked at them for a moment instead of shredding them to pieces. Now that my credit cards are all paid off, I actually thought for a moment about the time when the payoff on my car reaches the level of my credit limit on my highest card and that it might be a smart move to use one of these checks to pay off my car at that time, and then only be paying the low 1.9% (or whatever it was) interest rate on the principle.

However, I looked more closely at the checks, and noticed that nowhere did I see wording about a low interest rate, it actually took me a few minutes to find and see that now these checks are charged interest at the same rate as regular purchases, so it really would be no savings at all for me to use a check to pay off the car loan.

It got me thinking about when this change in interest rate for the checks went into effect. Was it months ago and I just didn't notice...know that I had no intention of using the checks?

How easy would it be for someone, who after months of receiving these checks with the low interest rate plastered all over them, to take the checks without looking closely at them and make some major purchase with them, not realizing that they were not gaining any savings whatsoever in terms of interest?

Just a small lesson as to the importance of looking closely at any paperwork you receive from financial institutions, and especially from your credit cards.

The 11 Best Money Saving Ideas of All Time - Part 3

Need extra cash for emergency bill but payday is too far away? NationalPayday.com can help with a cash advance up to $600!

Editors note: "B" is still swamped in the middle of a project, here is the third in a series of Money Saving Ideas from Palyn Peterson...

The 11 Best Money Saving Ideas of All Time - Part 3

by: Palyn Peterson

At any time in history, no matter what the current state of the economy, no matter what the current trends, no matter what the unemployment rate is or where interest rates lurk, some money-saving ideas stay true.

Some of you may have heard of these ideas before, others may be entirely new to you. But whether you are familiar with these super secrets or not, it will be well worth your while to put them into effect in your own life. The magic they will work on your financial life is guaranteed. I urge you to put them to work - any one of these could change your life! Big changes come from small steps. One plus one does equal two, so if you add one from eleven different places, you will see big results.

This is a four part series giving you advice on saving your hard-earned money in a variety of down-to-earth ways. Nothing here is anything that anyone can't do on a daily basis.

Amazing Money Tip #6

Do what you love and the money will follow. I think there's a book by that title. At any rate, it's true. One of the primary reasons that many people live paycheck to paycheck, and are broke despite working very hard at their jobs, is the fact that they hate what they do.

If you hate your job, you will not have a positive attitude toward money. You will associate money with that dreadful sound of the alarm clock every morning. Once you tie up your source of wealth and income with drudgery, that's exactly what the majority of your life will become: drudgery.

Starting today, you should begin planning your escape. The first thing you should ask yourself is: "If money were no object, what would I be doing? What do I like to do most for fun, and is it possible that I could get paid for it?"

Sound ludicrous? It's not. In fact, if your work is not also your play, you are fighting against yourself. You will eventually burn out and hate the world. On the other hand, if you get up every day being exciting, positive and looking forward to what you are going to be doing - and making money at it - you will automatically move toward doing more and more of what you love, and making more and more money at it. If your dream job means starting your own business, don't let that stop you either! It is much easier than most people think. Look in to it, it could literally change your life.

Amazing Money Tip #7

You must get organized. Being a tidy, efficient person has more influence on how much money you make more than you can ever imagine.

If you want to have a lot of money, you can't afford to be a slob. Think about it. Let's say you are at your desk trying to get some work done. You need to find the stapler, but because your office is such a pit, you spend 15 minutes looking for it. You've just spent 15 unproductive minutes. Next you may need to locate a file, and that takes you 20 minutes of sifting through paper. Another 20 minutes down the tube. By the end of the day, you may easily burn up two or three hours doing something as trivial as looking for things. The same goes for any kind of job you might have. If you are an auto mechanic, how much time do you spend trying to find a nine-sixteenth wrench, when you could have it at your fingertips.

It's disorganized people who are always saying at the end of the day: "I seem to work so hard but get very little done!" Of course! You spent the entire day looking for the Scotch tape!

The fact is, time is money. The more time you spend unproductively, the less time you are earning money. Clean up your office. Organize your tool shed. Get your bookwork organized. Think of every minute saved as a buck in your pocket.

Amazing Money Tip #8

Make your own daily top 10 list. Speaking of getting organized, you should sit down every morning with your cup of coffee and list the top 10 things you would like to get done that day. Then organize them in priority of importance. Start at item #1 and go down the list as fast as you can.

Make no doubt about it - this is a powerful way to get work done. It will put hoards of cash in your pocket. The reason is that making money is all about movement - forward movement. As the famous novelist Ayn Rand told us, in a capitalist society the most important things a person can do is move forward every day!

Having a top ten list will ensure that you accomplish something every day. You may not get through the whole list every day, nor should you necessarily try. Just do your best. At the end of the day, you should be able to look at your list with pride, examine the scratched off items and say: "That's what I got done today! I did something to better my life and create wealth!"

Again, this method has been used by a majority of the most wealthy and successful people in history. Shouldn't you join the club?

The next of the 11 best money saving ideas of all time will be discussed in part 4. Until then, take note of what you have learned so far and put this information to good use. Read and reread this article; I bet you will notice a difference sooner than you think.

Copyright © by Palyn Peterson

mailto:palyn@futureinternetmarketing.com

About The Author

Palyn Peterson publishes the acclaimed Advanced Internet Marketing News. A professional newsletter with a refreshing perspective and a strong focus on no-cost techniques. http://FutureInternetMarketing.com. FREE Tips, Tricks, Tools, Resources, eBooks, and More!

This article is free to publish with resource box. If using this article, please send a brief message to mailto:palyn@futureinternetmarketing.com

Thursday, June 30, 2005

The Get Rich Slow Scheme

Saga specializes in over 50's Car Insurance
---------------------------------

By Amey Stone on BusinessWeek Online.

5 Tips - More details on each by clicking on the link above for the whole story.

The truth is it's a lot easier to get rich -- and stay rich -- today by going it slow rather than latching onto a get-rich-quick scheme. Best-seller lists are clogged with books that explain in great detail how to Start Late, Finish Rich, or become The Millionaire Next Door. But much of the advice boils down to some pretty simple rules to live by. Here are five steps to slowly gaining the kind of financial security most people only dream of:
  1. Live below your means
  2. Take calculated risks
  3. Diversify your investments
  4. Keep your nose clean
  5. Keep your eyes on the prize

Wednesday, June 29, 2005

The 11 Best Money Saving Ideas of All Time - Part 2

The 11 Best Money Saving Ideas of All Time - Part 2

by: Palyn Peterson

At any time in history, no matter what the current state of the economy, no matter what the current trends, no matter what the unemployment rate is or where interest rates lurk, some money-saving ideas stay true.

Some of you may have heard of these ideas before, others may be entirely new to you. But whether you are familiar with these super secrets or not, it will be well worth your while to put them into effect in your own life. The magic they will work on your financial life is guaranteed. I urge you to put them to work - any one of these could change your life! Big changes come from small steps. One plus one does equal two, so if you add one from eleven different places, you will see big results.

This is a four part series giving you advice on saving your hard-earned money in a variety of down-to-earth ways. Nothing here is anything that anyone can't do on a daily basis.

Amazing Money Tip #4

Ben Franklin said it long ago: "A penny saved is a penny earned." Yes, it's still true, and still one of the most powerful money-making tips in all history.

Implied within Franklin's famous statement is the difficulty of saving. It's tough to save and easy to spend! You know that! That's why every penny saved truly is earned - because it takes so much effort to hold on to that cash! But if you can do it, it will work magic in your life. Having a savings account will de-stress your life. Imagine being ahead of your bills, rather than behind. When you are ahead of your bills, you entire life comes under your control. You sleep better at night. Your mind is freer to come up with new ways to make more money and save more. Saving is contagious - once you let it get started!

Here are some tips to help you save:

Don't settle for interest checking. Have a separate savings account that can't be as easily accessed as a checking account.

Keep your savings in another bank - one that's off your regular route, or perhaps even in another town. That way you won't be tempted to dip into it every time you visit the bank to make a checking deposit. (edit - or an Internet Bank, i.e. ING or VirtualBank)

Buy short-term savings bonds, which have 6-month to one- year maturity dates. That way you will get a higher rate, while at the same time keeping your money close in case of real emergencies.

If you can, open the account under two names and require that both signatures be required to make a withdrawal. Two people can debate each withdrawal and keep each other in line.

When you get your paycheck, immediately put a minimum of 5% in your savings account. After just a year, you'll be surprised by how much you have actually saved and feel great about it.

Amazing Money Tip #5

Visualize wealth and abundance everyday. Am I actually suggesting that you practice some sort of airy-fairy mysticism that will make you into a "money magnet"? Maybe yes, maybe no. Call it what you will - a mind game, mysticism, New Age ga-ga -- but the solid fact is that behind every wealthy man and woman is a positive attitude toward money. Here's a quick demonstration:

(1) Person One with a negative money attitude has daily thoughts which go this way: "Jeez! $20 bucks is hard to come by! I seem to work so hard and get so little for it. Money just slips through my fingers. It's amazing how much money you have to earn to just get by these days. I'm never going to be able to afford that new car on my limited salary, but this job is still the best thing going for me right now. It's easy for some people to make a lot of money, but I'm not one of those people ..." and on and on.

(2) Person Two with a positive money attitude has daily thoughts which go this way: "You know, I bet if I work my butt off I can get a raise next month, and then I'll take half of the extra money I make and toss it in a savings account. There must be a 100 other ways I can bring in some extra cash. Money is not all that hard to earn if you work hard, watch your spending and save a little at a time. There's enough wealth for everybody in this country, and I can easily get my share, and more ..." and on and on.

Okay. Which person do you think will have a better chance of success? You don't need to be a Rhodes Scholar to see how Person One is dragging himself down with his thoughts, and how Person Two is giving himself a fighting chance.

Look at it this way: It costs nothing one way or the other to have either negative or positive thoughts. So why not have positive thoughts?

There have been many studies done on the thought patterns and the frames of mind of some of the richest, most successful people in the world. The one thing they all had in common was a positive attitude toward money and their ability to earn it.

The next of the 11 best money saving ideas of all time will be discussed in part 3. Until then, take note of what you have learned so far and put this information to good use. Read and reread this article; I bet you will notice a difference sooner than you think.


Copyright © by Palyn Peterson

mailto:palyn@futureinternetmarketing.com

About The Author

Sign up for Palyn Peterson's FREE 13 day intensive email course and discover the 16 necessary basics and 8 advanced internet marketing techniques. You'll also receive a free $gift$. http://FutureInternetMarketing.com/guide.htm

palyn@futureinternetmarketing.com
This article is free to publish with resource box. If using this article, please send a brief message to mailto:palyn@futureinternetmarketing.com

Tuesday, June 28, 2005

The 11 Best Money Saving Ideas of All Time - Part 1

I apologize for the lull in posting there, just a lot going on right now. I hope to have a month-end statement by the end of the week, and for now, here's the first in a series of tips to help you save money...and simplify your life.

B

The 11 Best Money Saving Ideas of All Time - Part 1


by: Palyn Peterson

At any time in history, no matter what the current state of the economy, no matter what the current trends, no matter what the unemployment rate is or where interest rates lurk, some money-saving ideas stay true.

Some of you may have heard of these ideas before, others may be entirely new to you. But whether you are familiar with these super secrets or not, it will be well worth your while to put them into effect in your own life. The magic they will work on your financial life is guaranteed. I urge you to put them to work - any one of these could change your life! Big changes come from small steps. One plus one does equal two, so if you add one from eleven different places, you will see big results.

This is a four part series giving you advice on saving your hard-earned money in a variety of down-to-earth ways. Nothing here is anything that anyone can't do on a daily basis.


Amazing Money Tip #1:

The great scientist Albert Einstein once said, "It takes a genius to see the obvious." What he meant by that is that sometimes the simplest things in life are the most powerful ... but because they are so simple, we tend to ignore them, and not let them work for us.

One of the simplest but most powerful money making ideas is this: keep a daily log of everything you spend. Go to the dollar store and buy a little notebook and carry it with you wherever you go. Write down every penny - every single penny - you spend. It's as simple as that.

If you do this, you will find something magic happening in your financial life in just a few weeks.

There is something incredibly powerful about writing down all your expenditures. It makes the flow of money through your life more real and exact. It shows you simply and clearly just where you are spending your money, on what and why. Once you know that, it becomes much easier to control your spending.

Many people who have taken up this practice have not only learned something about themselves which they never knew before, but they are often astounded.

For example, a person could realized through examining their notebook that they actually spent nearly $2,000 throughout the year on diet soft drinks, snacks and candy bars! Since their job only brings in $25,000 per year, they realized that 8% of their entire income was being frittered away on something entirely frivolous. The person gave up the snacks and drinks, and found they had enough money to go on vacation the following year. If you had the choice between snacks or a much needed vacation, which would you choose?

The point is, it was their daily expense log that helped achieve the insight and clarity they needed to get control of their finances. That's what a simple spending record will do for you - it will give you control over your spending, and thus your financial life. There may be nothing but a 75-cent notebook and a ballpoint pen between your life of financial struggle and financial freedom.

Amazing Money Tip #2:

Stop deficit spending! We all know how much trouble Uncle Sam has been creating spending more money than our country takes in. It's called deficit spending. Well, don't fool yourself. The same rules apply to you. Using those evil little plastic cards may be the "American Way," but it's a darn poor way.

Today, the average credit card holder is carrying $8,000 in plastic debt!

Spending yourself into debt with a credit card is unbelievably easy, as many of you already know. The reason is psychological. When you give that clerk a credit card, it's just not the same as handing over a stack of green dollar bills. Would you as readily hand over a fistful of ten dollar bills as flip a credit card across a counter? Probably not.

Credit cards put you in the hole and keep you there. Even for people with good incomes, paying your credit card debt down to zero is amazingly difficult. And make no bones about it, credit card debt will sap your financial strength just as readily as an open vein will deplete your physical body of its very life force. Using a credit card by choice can quickly turn to using it for need. Once you get to that point, you are already in trouble.

There is no secret to freeing yourself from the credit card game. You must take out a pair of scissors today, cut your cards in half, and begin paying them back, slowly but surely. Be sure to always pay more than the minimum amount due, even if it is just $10 more. Once you stop adding to the debt, even small payments will eventually add up. You can get out of debt if you are patient and disciplined. Once your cards are history, you must adopt a strict pay-as- you go policy. Instead of buying now and paying later, save now and buy when you have the full amount.

Once again, this is not rocket science, but stopping credit- oriented consuming is one of the most powerful financial tools available to anyone today. Why not pick up this tool and use it?


Amazing Money Tip #3:

Sell your junk. That's right, it's high past time for a major yard sale. Search through your house or apartment for every single item you don't need, and could sell at a flea market or yard sale.

Take an inventory. The truth is, most people are astounded by what they own - and how much money they have tied up in useless stuff. Why let it collect dust in your attic while it could collect interest in a savings account.

You could easily be $500, $1,000 ... even $3,000 richer by the end of the week. As an added bonus, you'd have your place cleaned up, and you will have a fresh feeling of starting over. A garage sale is an excellent way to not only clean out your house, but it often gives a psychological boost that helps people get control of their life and money.

The next of the 11 best money saving ideas of all time will be discussed in part 2. Until then, take note of what you have learned so far and put this information to good use. Read and reread this article; I bet you will notice a difference sooner than you think.

Copyright © by Palyn Peterson

palyn@futureinternetmarketing.com

About The Author

Get the very same internet marketing techniques that many "guru's" are asking you $200 for -- FREE. Discover 24 necessary techniques. You'll also receive a free $gift$. http://FutureInternetMarketing.com/guide.htm

palyn@futureinternetmarketing.com

Friday, June 24, 2005

Finding Time to manage your Personal Finances

Terri Cullen of the WSJ online, who did a piece on Personal Finance blogs a couple of months ago, has an article today on "Finding Time for Personal Finances"

One paragraph in the article discusses a hard part for many...sticking with your program:

Now comes the hard part -- sticking with the program. Again, technology to the rescue. I use the appointment calendar in my office email program to send alerts to remind me which tasks require attention throughout the month. If the chore is critical -- say, paying property taxes or renewing my insurance -- I'll flag the appointment as urgent so I'm not tempted to put it off. For more routine tasks, I choose one day a week and block out the time in my calendar to handle the task. If I simply can't take the time at that moment to get the job done, I make another appointment during the week. If I punt on the task one more time, I reschedule and then flag it as urgent. No urgent task makes it through the end of the week undone. Period.

Wednesday, June 22, 2005

Microsoft Preps Money 2006

From Windows IT Pro:

Microsoft Preps Money 2006


On July 5, Microsoft will ship Microsoft Money 2006 to consumers. Microsoft Money 2006 provides new online banking tools and an all-in-one solution for consumers seeking to manage their finances.

"Money 2006 was designed to build on the rising trend of online banking by offering all of the consumer's financial information in one easy-to-use location," says Anne Quaranta, the senior product manager for Microsoft Money. "With the tools and information Money 2006 provides, consumers now have a complete view of where their money is and has been, and understand where it is going."

Money 2006 includes an enhanced spending tracker for managing expenses, the ability to pay bills from multiple accounts, and greatly improved investment tracking features. As with Microsoft Digital Image Suite 2006, consumers can preorder Money 2006 starting today at Amazon.com.

Money 2006 Standard Edition will retail for $29.95, while Money 2006 Deluxe Edition will cost $59.95. A Small Business Edition will cost $89.95. Each of these products will come with various rebate amounts, however.


I haven't decided if I will be an early adopter (might inspire me to get back at it with my Money transaction logging) or if I'll wait for reviews and see if it is worth upgrading.

Sunday, June 19, 2005

Car Payment Update

Just in case anyone was wondering, my situation from earlier in the week involving my car payment appears to have worked out ok. The $200 from PayPal arrived into my checking account on Friday morning. That gives me enough there to more than cover the larger car payment. I'll watch to see when that clears...perhaps tomorrow.

I've been reading "The Complete Idiot's Guide to Personal Finance in your 20's and 30's" and have found confirmation that I am indeed a complete idiot in a lot of the things discussed. Happily, I've gotten on the right track in a many areas and the book has really educated me on the basics of many others. I especially have found the chapters on investing to be helpful. I still have not taken much of a leap in that area yet. (I have a small account with Sharebuilder that I opened only to see how the process worked...my initial $200 is now worth about $140) I know however have a better grasp on what the various investing options are and how they work. I'll probably be re-reading the chapters a few times. I'm now getting into the section on buying a house, something that is still a ways away for me, but definitely in the mix somewhere.

I'd recommend that book to any young person who wants an simple overview of how to manage their personal finances. A more accomplished person will likely find many of the lessons elementary, but I guess that's why this is a "Complete Idiot's" book.

Friday, June 17, 2005

Good news on GBI

A few weeks ago I had done a little review on GBI Home Finance Manager. I'm pleased to pass on the news that thanks to a corporate sponsor, the program is now available to all users for FREE.

Free is always good.

GBI Home Finance Manager

Now you've got no excuse to go and check it out for yourself!