Friday, June 24, 2005

Finding Time to manage your Personal Finances

Terri Cullen of the WSJ online, who did a piece on Personal Finance blogs a couple of months ago, has an article today on "Finding Time for Personal Finances"

One paragraph in the article discusses a hard part for many...sticking with your program:

Now comes the hard part -- sticking with the program. Again, technology to the rescue. I use the appointment calendar in my office email program to send alerts to remind me which tasks require attention throughout the month. If the chore is critical -- say, paying property taxes or renewing my insurance -- I'll flag the appointment as urgent so I'm not tempted to put it off. For more routine tasks, I choose one day a week and block out the time in my calendar to handle the task. If I simply can't take the time at that moment to get the job done, I make another appointment during the week. If I punt on the task one more time, I reschedule and then flag it as urgent. No urgent task makes it through the end of the week undone. Period.

Wednesday, June 22, 2005

Microsoft Preps Money 2006

From Windows IT Pro:

Microsoft Preps Money 2006


On July 5, Microsoft will ship Microsoft Money 2006 to consumers. Microsoft Money 2006 provides new online banking tools and an all-in-one solution for consumers seeking to manage their finances.

"Money 2006 was designed to build on the rising trend of online banking by offering all of the consumer's financial information in one easy-to-use location," says Anne Quaranta, the senior product manager for Microsoft Money. "With the tools and information Money 2006 provides, consumers now have a complete view of where their money is and has been, and understand where it is going."

Money 2006 includes an enhanced spending tracker for managing expenses, the ability to pay bills from multiple accounts, and greatly improved investment tracking features. As with Microsoft Digital Image Suite 2006, consumers can preorder Money 2006 starting today at Amazon.com.

Money 2006 Standard Edition will retail for $29.95, while Money 2006 Deluxe Edition will cost $59.95. A Small Business Edition will cost $89.95. Each of these products will come with various rebate amounts, however.


I haven't decided if I will be an early adopter (might inspire me to get back at it with my Money transaction logging) or if I'll wait for reviews and see if it is worth upgrading.

Sunday, June 19, 2005

Car Payment Update

Just in case anyone was wondering, my situation from earlier in the week involving my car payment appears to have worked out ok. The $200 from PayPal arrived into my checking account on Friday morning. That gives me enough there to more than cover the larger car payment. I'll watch to see when that clears...perhaps tomorrow.

I've been reading "The Complete Idiot's Guide to Personal Finance in your 20's and 30's" and have found confirmation that I am indeed a complete idiot in a lot of the things discussed. Happily, I've gotten on the right track in a many areas and the book has really educated me on the basics of many others. I especially have found the chapters on investing to be helpful. I still have not taken much of a leap in that area yet. (I have a small account with Sharebuilder that I opened only to see how the process worked...my initial $200 is now worth about $140) I know however have a better grasp on what the various investing options are and how they work. I'll probably be re-reading the chapters a few times. I'm now getting into the section on buying a house, something that is still a ways away for me, but definitely in the mix somewhere.

I'd recommend that book to any young person who wants an simple overview of how to manage their personal finances. A more accomplished person will likely find many of the lessons elementary, but I guess that's why this is a "Complete Idiot's" book.

Friday, June 17, 2005

Good news on GBI

A few weeks ago I had done a little review on GBI Home Finance Manager. I'm pleased to pass on the news that thanks to a corporate sponsor, the program is now available to all users for FREE.

Free is always good.

GBI Home Finance Manager

Now you've got no excuse to go and check it out for yourself!

Thursday, June 16, 2005

Smart...or not?

I put myself in a bit of a bind this week. I mailed off my car payment yesterday, and paid an extra $200. Since I have had this car, I have paid extra in every payment except one, the smallest being $100, the most being $2000. Sounds good, you say?

Well, I have a confession...I haven't been keeping up with my entries in Microsoft Money. I've been keeping a rough estimate in my head about where my checking account is at during any given time. I check the on-line banking everyday, making sure what clears and what is still out there. If you've got plenty of money, it's not a problem.

My problem this time was that I forgot an item. So when the check for my car payment clears, I'm going to be right up against it. I also have my two $25 automatic withdrawals coming out tomorrow, (One to VirtualBank, the other to ING Direct). Now having money is not a problem, I've got my Paypal debit card and have been using that for my gasoline and misc expenses. I have enough to get through to next week. When the check goes through, however, I could be going into my overdraft protection, something I haven't done in some time.

For years I funded the Credit Union's annual Holiday parties with the fees paid from my account from going into overdraft. I've gotten out of that habit, and it's been probably close to two years since they've been forced to look elsewhere for their slush fund. But this time it could be close. I'm guessing the check is either going to clear tomorrow, or Monday. It seems to be stretching it that it could clear tomorrow, but with the new laws about electronic check clearing, it seems at least possible.

I put the check into a mailbox yesterday, which stated that the mail from that box was collected at 3:00 PM daily. I would guess it would go to the Post Office that night, be sorted, and be sent on it's way this morning, perhaps arriving in NJ tomorrow. If it arrives tomorrow, it needs to be processed. So I think I might be safe in thinking it will clear my account on Monday.

To try to make up the difference and get enough money into my account to ensure that I'm not paying an overdraft fee, I initiated a transfer of $200 from my PayPal account to my checking account. PayPal states that this usually takes 3-4 business days, which by that estimate means my funds will hit my checking account on Monday or Tuesday. However, my experience with PP has been that a lot of times it only takes 2 days. That means that money could be in my account tomorrow, which means things could work out. I'll be monitoring my checking account closely tomorrow and Monday.

Exciting, huh?

To reward you if you've read this far, here are a couple links you might find interesting. CNN Money has a list of the 50 Best Things to do with your Money. That page also has a link to the 15 Dumbest things you can do with you money as well. A lot of basic stuff, but some good reminders.
Oh yeah, I think probably everyone in the whole world has a Gmail account right now, but if you don't, and are looking for one, post a comment below with your current email address and I'll zip you off an invitation. I've actually had a Gmail account almost from the beginning, but haven't been spreading out the invites that I have. Guess I should be better at sharing.

Tuesday, June 14, 2005

June = Car Registration and Inspection time

My date of birth is in June, so this month I need to get my auto registered and inspected.

I live in NH, and this is an annual requirement. I've always dreaded the inspection part, because it seems like a conspiracy to get garages business. You are totally at their mercy. If they deem that a portion of the inspection gets a failing mark, then you are required to get the repairs done within a certain amount of time...I believe 20 days, and you cannot go elsewhere to try to get another inspection...it has to be done at the place you got the original done.

Garages know that you're likely to just have them do any necessary work, so I don't think it's out of the realm of possibility that many places arbitrarily fail some vehicles just to get the extra business. It doesn't quite seem right to me.

I understand and even appreciate the need for an annual inspection. It keeps a much higher percentage of safe cars on the roads. I just wish there could be a system of checks and balances to ensure that consumers are not being taken advantage of. I know that if the mechanic passes your car when it is in fact not safe, and you then get into an accident, or are pulled over and the officer notices something wrong with your car, that the mechanic that issued the passing sticker can be sanctioned. But what do we do about unnecessary repairs which the mechanic may basically force you to have done by withholding a passed inspection?

This has been an issue with me since I was in my late teens and had a vehicle I thought would have no problems with the inspection process. $800 later I knew better. Now each year since then, I've approached each inspection period with a feeling of dread. For a number of years I've gone to a small garage which does check many of the major items, but will let you slide on some of the things perhaps a bigger garage would nail you on. Each year I'm afraid this place will no longer be in business. I have to call them in the next week or so to find out.

A new thing this year is NH is doing emission testing for the first time. This is another cause for my concern over the place I usually go to. I fear they won't have that equipment and won't be able to do the testing.

My car is a 2000 model and in very good shape, I take care of it, I've gotten new tires this year, had the brakes done last year. It should be all set...but still I fear...am I going to have to shell out big bucks in repairs...that I might not need?

Tuesday, June 07, 2005

Next Mission: Reduce Food Bills

More confession time.

My biggest shopping weakness is food. Expensive/gourmet food items that sometimes just end up sitting unused on my shelves until they go bad.

I'm pretty good with almost all other areas of shopping and spending money. Clothes aren't a problem, gadgets appeal to me, but I can generally control myself in that area. Books are occasionally something I'll spend a bit on, but I try to justify the purchases I make. Food...now that is a problem.


I'm a sucker for good food, and even though I know it's not always necessary, most of the time, I look for the best ingredients, or go with a "name brand". I know enough not to go food shopping when I'm hungry, so I don't have that excuse for my grocery bills.

I do try to eat healthy, and I know that contributes to the expense. Most high quality foods are going to be more expensive. Whole grain or Organic products just aren't cheap yet. I don't go organic with most of my produce, but with certain items, if they look better than the regular produce, I'll pay the higher price for the Organic.

It's not unusual for me, a single guy, to spent $80 - $100 on groceries in a single week. I do cook in the evenings, so I try not to eat out all that much.

I'll go down the aisles see something that looks "neat" or interesting, and throw it in the cart. Trader Joes is a place where this is extremely easy to do.

What do I do? I make menus and compose grocery lists of only the things I will need for the things I plan to make and eat that week. A few extra things always find their way into the cart.

One theory I have is that grocery items are mostly small ticket items. You don't think of $2.99, $1.79, $2.59, $3.49, 2 for $4.00 as being all that much, until you add them all up. "It's only a couple bucks". It adds up very quick.

If I'm going to really simplify and make the money that I have go further, I need to spend less at the grocery store. I should be able to cut the weekly bill in half. That other half needs to be working for me elsewhere.

Monday, June 06, 2005

GBI Followup

Just a follow up to the CBI software review that I mentioned last week. I got an email from the make of the product, who says:

We have also realised that the US market is defnitely on of our biggest ones. That's why we have decided to have a US version.

In essence, the US version is the same as the other version but your dates are showed in US format (i.e. mm/dd/yyyy). You have the option to change that if you want. We are using IP addresses and a country-ip lookup table to determine the location of the visitors.

Also, to make it more competitive and to eliminate exchange-rate fluctuations, we have made the US version $20 per year (which I think is quite good). If you login to the site now and your IP address is a US one, you will be redirected to the US edition and the cost will be showed in USD.

We also have a UK version (in pounds) and an international version (in Euro).

Wednesday, June 01, 2005

June snapshot

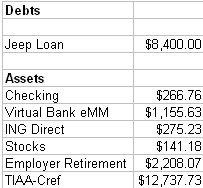
So here is where I stand at the moment.
No credit card debt, still a sizable chunk left on my car. My goal is to have it paid off by the end of the year. Then have a car with some life left and start the savings process towards the goals of living a simplified life. This weekend I found an interesting book on the topic, which I plan to review here soon.

Compare that to this one, which is where I was last October, or eight months ago.


Nice to see some visible progress. While it may not be as dramatic as some that I've seen on other blogs around cyberspace, as a financial newbie, I think I'm doing pretty well...much better than I've ever done in the past. I hope to keep up the progress and avoid any setbacks, but of course those can't all be anticipated.

One area in which I need to write about soon is my spending the area of groceries and food. That is easily an area in which I can cut back, but haven't been able to do so thus far...I love good food!

GBI Home Finance Manager

I've chronicled on here my adventures in using Microsoft Money and Quicken. I seem to have stuck with Money for the moment, but I should be using the Quicken for the small business side of things. I'll look into that.

There's another option that I've become aware of and that is the GBI Home Finance Manager, which is basically an on-line version of the previously mentioned programs. You can check out the program at the following location:

https://www.globi.co.uk/gbifin/ (Or you can click on the banner in the right hand column)

Right now they're offering a free month to try it out. As with most of these type programs, it takes some time to set up all your accounts, but once you've got them in there, you have the advantage of being able to access them from anywhere. This is a bonus for people like me who like to enter your transactions as soon as possible. (Like filling my gas tank on the way to work and then entering that when get to work.)

The first thing you might notice is that currency is listed in pounds. Don't worry, you can change your preferences. It works with the dollar. While you currently cannot link to accounts and get automatic updates to those accounts, I'm told that this is something that they are currently working on adding to the program.

You can however, import both Money and Quicken files into the program. This is a help. The program seems a bit sluggish at times, but that is probably to be expected with a web based program like this one. You've got a menu bar, which stays with you as you scroll through the program. The menus are as follows: "At a glance" "Manage" "Analyse" "Administrate" "Help" and "Links"


Menu

On the menus you've got a lot of options, which make this more than just a Finance application, it's also a Personal Information Manager. You can add links to websites, add contacts, create documents, do a mail merge, and set up reminders.

All in all, I was quite impressed with the versatility of this on-line application. If they can set up a way to sync with various online accounts, the product will be even better. It's priced at about $28 for the year, so it is competitive with what you're going to pay to upgrade MS Money or Quicken each year.

Wednesday, May 25, 2005

Sweet...

Contact Budget for Budget Cheap Travel Insurance in the UK
--------------------------


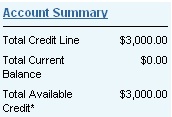
That's a beautiful thing. It's my last credit card account as it looks now.

No, I'm not gloating.

Tuesday, May 24, 2005

New Monitor

The fund drive at my other site was a success. $1500 brought in. That paid off my residual credit card debt, (I had a couple hundred on one of the cards from my vacation last month.) Now my only debt is my car payment. I don't have a cell phone bill, I get unlimited calls from Vonage for $25, I'm paying for my gasoline through the PayPal account, and the only other monthly bills I have are car insurance, electric and cable. (and Rent, of course) The next step is getting my food budget under control.

I got a new 19" flat panel monitor from Dell that I had been looking at...$300...normally it was at $480 or more. I justify this purchase with the fact that my old 15" monitor is now 4 years and I can use it for other things. I plan on doing more and more web stuff and need a good monitor to do it all on. The fact that I got a good deal on it was a bonus. The rest of my money is targeted to boost my checking account and some for savings.

I need to spend some time brainstorming ideas for my other webpages. The goal is still to simplify my life to the point that I can work from home, doing the things I have a passion for.

Save at Overstock.com!

Thursday, May 19, 2005

Why the fuss over PayPal?

Some of you might have wondered why I made such a fuss over PayPal last week. Sure it's nice, but can't I live without it?

Not this week, I couldn't.

See I used it this week to make money. I have another website - several actually - but one that gets quite a lot of traffic. I've had it up and running for three years now. It's not really something I can sell, so I was stumped as to how I could make money from it. I decided in the end, one of the best ways to make money from the page was to do it the old fashioned way.

I asked for it.

The site provides a niche service that many people take advantage of. I'm hesitant to name the site here as I don't really wish for the two to be connected at this time. I want to keep them separate. There's a lot of research involved in keeping up the other site and people are appreciative of it. In the beginning I would get random donations here and there from people, but I decided to make it a concentrated effort. I used to work at a PBS TV station, so I know a little about running a fund raiser. I decided to use similar principles and run two fund raisers a year for my site. A major one in the fall, and a smaller one in the spring. Two years ago, I had my first fall drive, set a goal of $3500 and made it. Last May I set a goal of $1500 and made it. Last November, the goal was $5000, again it was made, and this week I'm again going for $1500. As of this moment, I'm at about $1100 with a day to go.

My point during the drive is to talk about the time and effort I put into the site. (2-3 hours each day) There are also considerable expenses involved in maintaining it. I recently had to double my bandwidth capacity with my hosting company. People are appreciative, and many drop in $10, $25, $50, some even $100. I have them send it via PayPal. Sure, PP skims a little off the top, but for ease of use it can't be topped. I've got the Debit Card from them, and it's easy to move money into my banking account.

There are other ways I make a little money from the site. Google Adsense, Amazon.com Affiliation and some banner ads, but it's nothing compared to the Fund drives I put together. These are the main source of revenue from the web for me. I use the money to pre-pay hosting and design, upgrade equipment and to justify the time I spend working on the site. I've been able to pay some debt down with it as well.

So there you...if you wondered why I was making the fuss over PayPal...there's your answer.

Wednesday, May 18, 2005

Degunking your Personal Finances

I recently received a review copy of Degunking your Personal Finances by Shannon Plate, and after a brief perusal, I am enthusiastically looking forward to reading the whole book. When I do that, I will provide a full review here, but here are a few tidbits to whet your interest. It seems to be laid out similar to the "Dummies" and "Complete Idiot" book series which have proved so popular...however at first glance it appears there is more here than just the basics. This is a pretty big book...334 pages in all.

The book revolves around a 12 Step process that you should follow in order to fully degunk your personal finances. The steps are:

  1. Get your financial life organized and set aside a place in your home to work on your finances.
  2. Create a clear picture of your current financial situation.
  3. Clean up your credit and debit cards.
  4. Get your consumer debt under control by paying it down.
  5. Fine-tune your home mortgage, and put measures in place to lower your household and other living expenses.
  6. Put a program together to boost your savings and investments.
  7. Clean up your credit report and improve your FICO credit score.
  8. Fine-tune and optimize your budget and improve your spending habits for transportation, groceries and other activities.
  9. Get your taxes, employee benefits, and insurance in better shape.
  10. Find hidden money you didn't know you had.
  11. Put your computer to work to help you automate managing and tracking your finances.
  12. Improve your financial security, avoid identity theft, and put a good back-up recordkeeping system in place.
In the book, there are one or two chapters devoted to each of these 12 steps. If you don't have a lot of time, there are also several quick ways in which you can degunk in 15 minute, 30 minute, one hour, three hour and half day segments.

As mentioned, I'm enthusiastic about this book and look forward to reading and bringing you more about it in the weeks to come.

Friday, May 13, 2005

Simplifying your life in 2005

As seen on Lifehacker this morning.

Lifestyle tips: How to simplify your life in 2005

  • Tip 1: Direct debit everything.
  • Tip 2: Cancel call-waiting on your home phone.
  • Tip 3: Make sure you're not always-on.
  • Tip 4: Read more books and long magazine articles, less on the Internet.
  • Tip 5: Cancel your subscription to cable TV, and subscribe to a movie-rental service instead.
Go to the link above for details on each one of these tips.

Or, on the other hand here are Five Habits of Millionaires so you can act like one.

Oh, and by the way, after a phone call from me, my PayPal account is now fully restored. Now I can plan out my fund drive for one of my other sites that will be for next week.

Tuesday, May 10, 2005

No PayPal Resolution

I'm still annoyed with PayPal. I was away for a week, (Thus the lack of posts) and when I got back Saturday night, I had finally received my letter from PayPal with my important 6 digit code that I need to enter on the website so that I can get my account out of "limited access".

I go to PayPal, log in, enter my code, figuring I'll finally have access to my funds, and also send out some invoices. Instead I get the message thanking me for confirming my information, and that now a representative will have to personally review my account and that I should have an answer within 3 business days.

This is borderline rediculous. To clarify, I've had this account for 3 plus years, have always done the verifications and have never had a single issue. I just hope to be back on it in the next couple days...

The vacation was a success, and pretty cheap, too. Other than 15+ hours of driving, the week was relaxing, got plenty of sleep, ate good food and got some sun and beach. Total cost for the week was probably under $500. Sometimes you just need to get away.

Monday, April 25, 2005

PayPal Annoyance

Get a Home Insurance quote from Direct Line in the UK

-----------------------
I'm annoyed with PayPal.

I probably shouldn't be.

I got an email last week informing me that they have "limited access to your account until additional security measures can be completed". Initially, I took this with a grain of salt, as I get these types of emails fairly often, and they're always "phishing" scams. But this email had no link to click on in it, giving me the impression that this might be legit. So I signed into my PayPal account, and sure enough, I'm on limited access. I can receive money and payments, but I cannot transfer money or make any withdrawals until I update my security information.

The reason given is "unusual activity" on my account, which, to me, the only thing I've been doing differently is I've been using my new PayPal debit card to pay for gas in my car and a couple of other purchases. This is unusual, apparently.

So I go through and start completing the security checks. There are three levels you have to complete. I do the first two easily, stuff like changing your password, answering some security questions like mother's maiden name, last 4 digits of SS# and a couple other things. Then the third step. They want your phone number so they can match it to your home address.

There's the problem. I use Vonage as my home phone number and apparently PayPal can't connect a phone # to a physical street address on a Vonage phone as they would be able to on a regular phone. So I fail that test. What they need to do now is mail me, via snail mail, a 6 digit code to my home address, and when I get that, I can go to the PayPal page, enter it, and hopefully complete my security check. They say it should take 5-7 business days to get that code.

Here's my problems. I'm going on vacation next week...leaving this Friday night. If the code doesn't come before then, I won't be able to use my debit card at all while I'm gone. Second, my other website hosting is bill through my PayPal account. If I haven't validated my account before the 1st, the payment will not go through. I will have to make alternative arrangements...perhaps. I'm planning on switching over my hosting the end of the week to a less expensive, but more full-featured plan. That's all part of a busy week here.

I suppose I should be grateful that PayPal is beefing up security in this manner, but I wish my account didn't have to be basically shut down for a week and half and punish me, even though no security was actually broken.

Thanks to all who participated in the guest blog entry with Tripp Friedler, there were some interesting comments posted.

Monday, April 18, 2005

Guestblog Entry from Author Tripp Friedler

This is a post from Tripp Friedler, author of "Free Gulliver" over the course of the next few days Friedler will respond to comments made by readers. We look forward to a good exchange of ideas here on Simply My Life...

First I would like to thank Bruce for allowing me some air time. I feel right at home here because my book is all about simplifying your life. It is about cutting all those pesky little things that tie us down. It is about getting freed.

I have done many things over my career (restaurateur, record producer, fashion photographer) but for the last 15 years I have been involved in financial consulting. I have worked with numerous clients and I began to notice that they all had the same basic issues. They were focusing so much on accumulating wealth that they were forgetting about having fun. My book is about getting rich but it has very little to do with money.

One issue most relevant to many of my clients is retirement. Somehow in our society retirement has become a good thing. In fact, many people today will stay in jobs they hate just to be able to save for retirement. In some ways this is like getting married, coming back from the honeymoon, and stating that you cannot wait for the divorce.

If we look at really successful people, they do not "retire." In fact, Suze Orman who preaches about retirement is herself not retiring. She has plenty of money yet continues to work. She understands that when you do what you love you never want to stop.

I know many people will say, "Easier said than done. I hate my job but at least it pays well." My question is; what is the appropriate trade off between a job you hate that pays well and one you enjoy doing that pays less?

So I would like to end with the following question: Do you think it is smarter to do work you love and save very little or work you do not like and save a lot?

email: TRIPP FRIEDLER
Author of "Free Gulliver: Six Swift Lessons in Life Planning"

Thursday, April 14, 2005

No more credit card debt!

Alright, so the money was transferred to my bank account and I paid the credit card debt. Actually I will still have a balance of about $100 on there, but I will pay that in the next couple weeks and then stick the credit card in my desk where I won't have it with me.

My plan of using my PayPal debit card to pay for my gas is working out good thus far this month, and it's been needed. Things are very tight this month, and in three weeks I'll be spending a week in the Outer Banks in North Carolina. Some friends of mine rent a house out there once a year or so, and it's a huge house and after we all split the cost, it only comes to about $150 per person for the whole week. We also divide up the making of the meals, so that each couple or pair is responsible for providing food on one day. We drive down there, so all in all, it is a very inexpensive week of vacation.

I'll try to get together a snapshot of my financial picture here sometime like I used to do....

More on "Free Gulliver"

More on "Free Gulliver", the book by Tripp Friedler, who will be a guest on this blog next Monday, April 18th.

Scheduled to publish April 16, the book acts as a swift kick in the pants to remind those people who have just finished their taxes that now is a good time to plan their lives.

Free Gulliver takes the conventional wisdom of financial planning -- how to get what you need to do what you want -- and turns it upside down: how to start doing what you want, *now*, and how to deal with the financial fallout.

As a nation gets nervous about Social Security, Friedler reminds us that "you never retire from a job you love." He'll show you how to stop saving for retirement and start building a job you never want to leave: one that will provide you with income into your second century.

Parents struggling to save for college might be surprised at Friedler's advice: Try cutting back on work and sharing that time with your kids, even if it means less money for college. "The time you spend with your children pays bigger dividends than any investment you will ever make."

Tripp Friedler is an attorney, estate planner, chartered life underwriter, and Gulliver-gone-wild. He is the father of three children. Free Gulliver helps people rig their finances to achieve life goals. It's a swift trip. Won't you give it a ride?

A listing for the author's blog tour:

The "Never Retire" Blog Tour
Featuring Tripp Friedler, author of "Free Gulliver"
Starting Monday, April 18, 2005, at the following blogs:

* All Things Financial

* Simplify My Life

* The Budgeting Babe


Here's some more from the publisher of the book:

Do the turbulent waters of a troubled economy find you looking for a life jacket? Are you trying to get ahead but feel like you're treading water? Do you come home exhausted at the end of the day, unable to muster the energy to pursue your dreams in your "spare time"? Do you feel tied down by the little things, unable to tend to your life goals because just tending to your life is too taxing?

Maybe you're a Gulliver? You remember: Big guy, gets in a shipwreck, swims to shore, exhausted, falls asleep. Wakes up in the morning to find Lilliputians have tied him down - - little guys with tiny strings -- so he can't move. Ever feel like Gulliver? Sure you have. We all have. The time has come to cut those knots.

Free Gulliver is a little book for big people. It will help you slice through those knotty problems that keep you from doing what you were put here to do. You remember what that is, don't you? That thing you put on the back burner so long ago an hour in the microwave wouldn't thaw it. That gift you have. That natural talent you can't find an outlet for -- can't afford to pursue -- not until you get your debts paid down, not until the kids are in school, not until the kids are through college, not until you retire... Little things. Lilliputians with little strings. Keeping you from the life you love.

Free Gulliver will show you how to cut through those lines, little by little, and get moving again toward the life you love. It's written by Tripp Friedler, an attorney, estate planner, chartered life underwriter, and Gulliver-gone- wild. Tripp has studied the life plans of the rich and famous and found out -- guess what? -- they're just as stuck as the rest of us. Friedler has made a business of helping people get their lives back on track. He can help you, too.

Free Gulliver: Six Swift Lessons in Life Planning will help you:

Remember what you're supposed to be doing here
Take an honest look at where you're life journey is right now
Free up the time and money you need to be you
Find unexpected ways to express your natural talents
Make a life plan that realistically gets you from here to there

Free Gulliver turns financial planning upside down (as if your finances haven't been through enough upsets lately). Instead of helping you have enough money when you retire to do what you really want to do, it helps you start doing what you want today, because you never retire from a life you love. Free Gulliver will help you find meaning and fulfillment while still generating the income you need to get by. It will liberate you from the little things that tie you down. It's a swift trip. Won't you give it a try?

ENDORSEMENTS

"For those who feel that things have gotten too complicated, too tangled up, too damned crazy, this book offers candid, straightforward, and practical advice. There is real help here, and the calm voice of someone who's been there and found a way to make his own life better. It's the kind of help we can all use from time to time."
-- Alan M. Webber, Founding Editor, Fast Company

"For all people who want to simplify their lives and still reach their goals, Tripp Friedler has written a delightful and useful book. It shows how to clarify your vision and focus on what's important. With real case studies and reference to his own journey, Friedler makes his lessons wonderfully readable."
-- Walter Isaacson, CEO, The Aspen Institute

"Tripp Friedler uses straight talk and apt illustrations to teach how to free ourselves and find the meaning that lies waiting in every life. By following his own passion, he helps us realize ours."
-- Peter White, Wealth Advisor

"This book is terrific. Traditional, financial life planning leaves you believing that the proper asset allocation or security selection will bring happiness. This is not the case. In order to live a full life everyone needs to ask the questions that are presented in this book. Friedler challenges the reader to think, discuss and set the groundwork for a balanced and fulfilling life. It is truly a shame that this aspect has been left out for so long."
-- Peter Ricchiuti, Assistant Dean, A. B. Freeman School of Business, Tulane University and Director Of Research, Burkenroad Reports

"Tripp Friedler, using his own life experiences, takes us on a wonderful journey. Along the way, we learn to better understand how our career and retirement can become more meaningful and satisfying to us. We also get to learn the importance of defining the legacy we will leave for future generations. He helps us enjoy the journey and achieve our goals."
-- Frank Helsom, Former CEO, Bessemer Trust

"With an unusually caring and human voice, Tripp Friedler explains how having a better life comes down to making simple choices. Friedler uses plain language and real-world examples to guide readers through a decision-making process that can profoundly improve their lives. For anyone stressed out about the quality of their life and what the future will bring, this warmly written book will help you see-and realize-your own possibilities."
-- Keith Mcallister, Media Consultant, Former Executive Vice President and Managing Editor, CNN